Leadership
Before You Make a Decision You Can't Easily Reverse
How to build a Case for Change that helps boards understand the alternatives, uncertainty and consequences before making a difficult-to-reverse decision.
Jamie McCann · · 10 min read
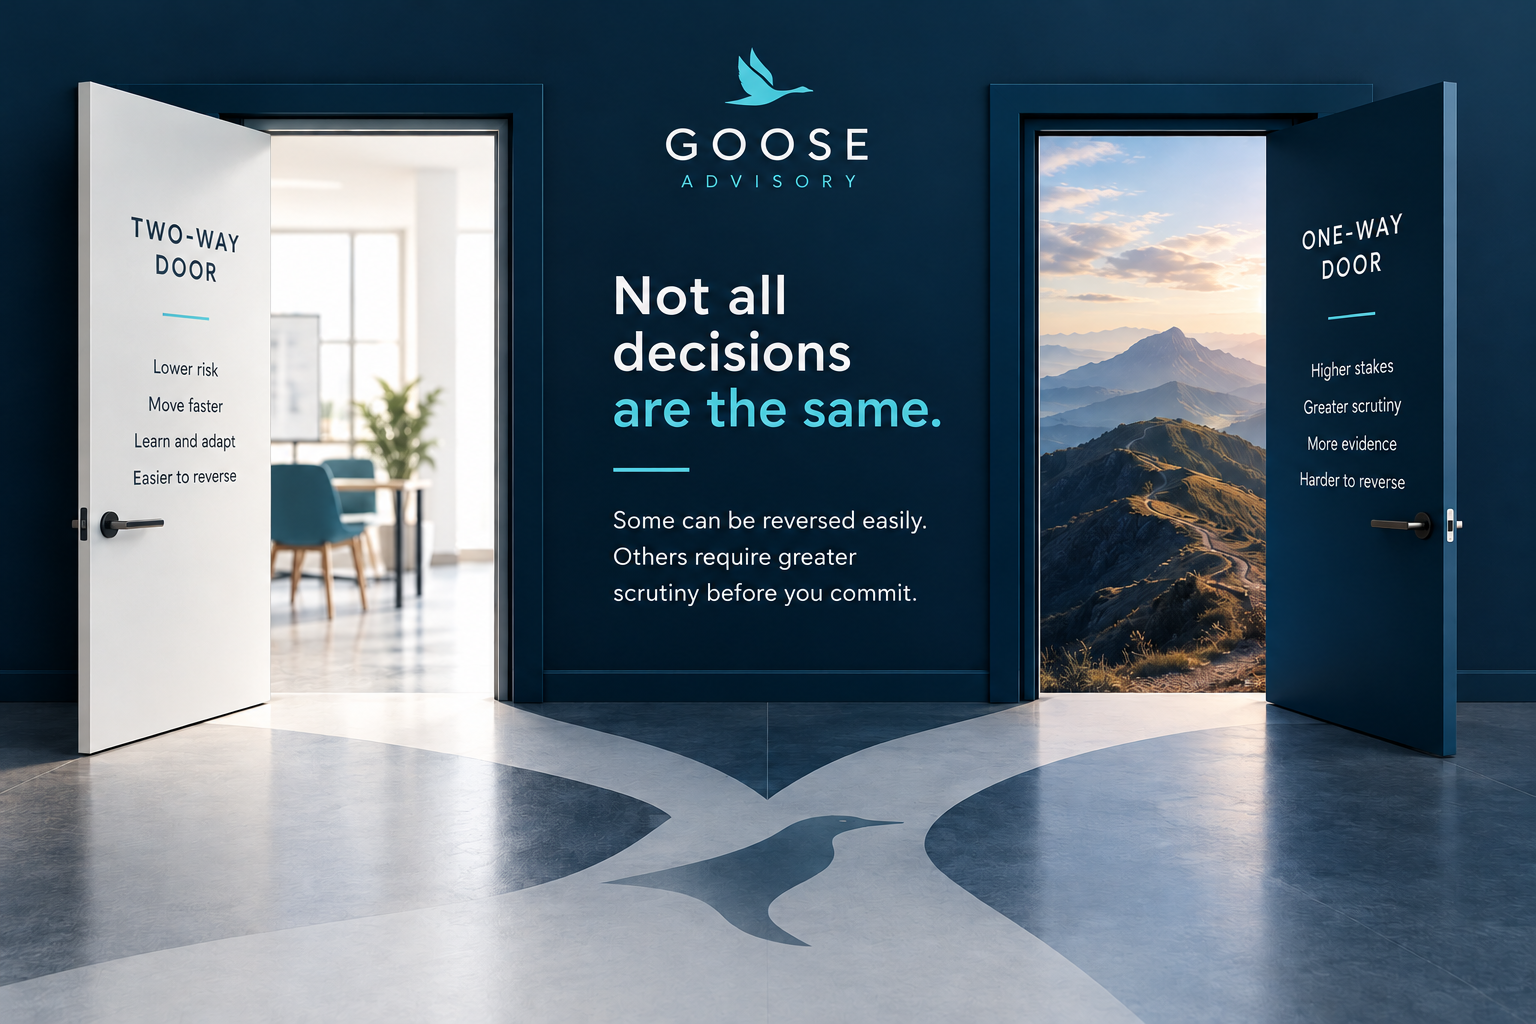
In an earlier article, The Architecture of Better Decisions, I explored how businesses can improve decision-making, including the distinction between one-way and two-way door decisions popularised by Jeff Bezos.
Some decisions are relatively easy to reverse. We can make them quickly, learn from the experience and change course without disproportionate cost or disruption.
Others are much harder to unwind.
Acquisitions, major technology investments and fundamental changes to a business model can commit capital, people and reputation in ways that are difficult, expensive or sometimes impossible to reverse.
These are one-way door decisions.
My earlier article explored decision architecture, including matching governance to how reversible a decision is. This time, I want to explore the other side of the equation: how should we approach decisions that are difficult to reverse? And what should a compelling Case for Change look like when the consequences of getting it wrong are significant?
One-way doors need a different standard
The distinction isn't always absolute. But it is a useful way of deciding how much analysis, challenge and governance a decision deserves.
A relatively reversible decision might need a clear objective, sensible controls and a quick review. A one-way door decision needs more. It needs a compelling Case for Change.
The greater the consequences of getting a decision wrong, the more important it becomes to understand the evidence, assumptions, alternatives and risks before committing.
Start with the decision, not the analysis
I've seen plenty of business cases that contain a great deal of information but make it surprisingly difficult to understand what the board is actually being asked to decide.
I prefer to start with the recommendation.
What are we proposing? Why? What will it cost? What do we expect to gain? What could go wrong? And what happens if we do nothing?
The supporting analysis should then explain why the recommendation makes sense.
That doesn't mean deciding the answer before examining the evidence. It means structuring the paper around the decision once the analysis has been completed.
A good board paper shouldn't force directors to work through twenty pages before discovering what management wants them to approve.
A fictional acquisition
To illustrate the approach, let's consider a fictional acquisition.
Goose Advisory has an opportunity to acquire Risky Insurance Brokers Ltd, an established commercial insurance broker.
The business generates £2.6m in annual revenue and £680,000 in EBITDA. The proposed purchase price is £4.2m, equivalent to approximately 6.2 times EBITDA.
The strategic attraction is recurring commission income, a new distribution capability and opportunities to develop the business.
But the acquisition would also commit substantial capital, introduce regulatory and integration responsibilities, and create risks that would be difficult to reverse.
For this fictional example, the board is being asked to approve confirmatory due diligence, not the acquisition itself.
That is an important distinction. The decision to spend £40,000–£60,000 investigating an opportunity is materially different from the decision to commit £4.2m to buying it. Good governance should recognise the difference.
Download the worked example: Acquisition of Risky Insurance Brokers Ltd — fictional Case for Change (PDF)
The eight-page PDF, including its cover, illustrates the strategic rationale, alternatives, financial modelling, execution risks and recommendation. The business, transaction and financial figures are fictional. The paper is a demonstration of a decision-making approach, not an actual acquisition proposal. The companion PDF is available to download using the link above.
1. Is there a compelling strategic reason to act?
Before getting lost in financial projections, I want to understand the strategic case.
What problem are we solving? What opportunity are we pursuing? Why is it important now?
In the fictional acquisition, the argument is that consultancy income depends heavily on the time of experienced individuals.
Acquiring a broker would introduce recurring commission income and give Goose a business in which to apply its commercial and analytical capabilities.
That is a plausible strategic rationale. But it isn't enough on its own.
The board should challenge whether owning a broker is the best way to achieve those objectives.
Which brings us to the alternatives.
2. What else could we do?
A Case for Change should explain why the proposed course of action is preferable to realistic alternatives.
In this example, the alternatives include growing the consultancy organically, establishing a commercial referral partnership with a broker, or doing nothing.
Each offers a different combination of investment, risk, control and potential return.
Organic growth avoids acquisition and integration risk but may not provide the same recurring revenue.
A referral partnership could create commercial opportunities without committing substantial capital, although it would offer less control.
Doing nothing preserves capital and management capacity, but leaves the underlying strategic question unresolved.
The important point is that alternatives should be genuinely considered, not included simply to make the preferred option look attractive.
3. What do the economics really tell us?
This is where I think many business cases could be improved.
Most business cases I've encountered rely on a central forecast, sometimes accompanied by optimistic and pessimistic scenarios. There's nothing inherently wrong with that approach. But it can create a misleading impression of certainty.
In reality, several important variables are uncertain at the same time.
Monte Carlo simulation is a well-established technique for modelling that uncertainty. Yet, in my experience, it remains surprisingly underused in business case development, particularly given how much it can contribute to better risk-based decisions.
Rather than relying on a handful of predetermined scenarios, we identify the important uncertain variables, define reasonable probability distributions and run the financial model thousands of times.
Each simulation produces a possible outcome. Taken together, those outcomes allow us to examine the range of potential returns, the likelihood of different results and the assumptions that have the greatest influence on the investment case.
This changes the conversation in the boardroom. Instead of simply asking whether the forecast return is attractive, directors can ask:
- What's the probability of losing money?
- How much could we lose?
- Which assumptions are driving that risk?
- What would need to change to improve the outcome?
- Is the potential return sufficient to justify the uncertainty?
The objective isn't to make the financial model more complicated. It's to make the decision better informed.
What might the simulation tell us?
In our fictional example, the accompanying paper reports 20,000 simulated scenarios:
| Measure | Illustrative result |
|---|---|
| Median three-year NPV | +£400,000 |
| P10 downside | −£500,000 |
| P90 upside | +£1.4m |
| Probability of positive NPV | 72% |
P10 and P90 are percentiles of the simulated outcomes. P10 is the 10th percentile, meaning 10% of simulated results fall below it; P90 is the 90th percentile, meaning 10% fall above it. P50 is the median, with half the results on either side.
In this example, approximately 10% of simulated outcomes have an NPV below −£500,000 and 10% exceed +£1.4m. These are not absolute worst- and best-case results; outcomes can fall outside that range.
A conventional presentation might concentrate on the positive £400,000 median return. But the distribution tells a more interesting story.
Under the modelled assumptions, 72% of simulated outcomes have a positive NPV and approximately 28% do not. This is a modelled valuation result, including an assumed continuing value, rather than a probability of recovering the purchase price in cash within three years.
The board can now have a much better conversation. Is that level of risk acceptable? Could the business absorb the downside? Are the assumptions credible? What would need to change to make the investment more attractive?
And, crucially, which assumptions have the greatest influence on the result?
These are reported outputs from the fictional worked example, not independently re-run forecasts. The case simplifies cash conversion, tax and capital expenditure. Its three-year NPV includes an assumed continuing value based on EBITDA and a valuation multiple; that value is not cash proceeds from a planned sale. The full reproducible model and complete sensitivity tables are not included in the companion PDF.
4. What really drives the outcome?
A simulation becomes particularly useful when we examine which assumptions are driving the results.
In the fictional acquisition, the accompanying analysis identifies synergy delivery, integration costs, the continuing valuation multiple and key-person retention as important sources of uncertainty.
That should influence the questions the board asks.
How credible are the synergy assumptions? What evidence supports the integration budget? How dependent is the business on a small number of individuals? How sensitive is the valuation to changes in profitability?
Rather than treating every risk as equally important, we can focus attention on the assumptions that materially affect the decision.
This also helps management identify where better information would be valuable before committing.
5. What are we really committing?
The financial model is only part of the Case for Change.
Major decisions consume management time, organisational capacity and attention. Those costs can be just as important as the financial investment.
In the fictional example, due diligence would consume approximately half the CEO's time for six weeks. Integration would require sustained leadership attention while the business was already developing other capabilities.
So what stops, slows down or becomes more difficult? Which existing priorities are displaced? Who will lead the work? And what happens if the project takes longer or costs more than expected?
I think every significant Case for Change should answer those questions explicitly.
Otherwise, we're approving an investment without fully acknowledging what the organisation is giving up to pursue it.
6. What could make us change our minds?
For a one-way door decision, I want to see more than a list of risks and mitigations.
I want to know what evidence would cause us to reconsider the recommendation.
In the acquisition example, that might include unacceptable customer concentration, material regulatory concerns, higher-than-expected employee retention risk or a purchase price that no longer supports the investment case.
These should be genuine decision gates.
Due diligence isn't simply an exercise in confirming the recommendation management has already made. It is an opportunity to discover whether the recommendation should change.
The ability to walk away remains valuable until the irreversible commitment is made.
7. How will we know whether the decision worked?
A good Case for Change should also establish what happens after approval.
Who is accountable for delivery? What milestones matter? Which assumptions should be monitored? When will performance return to the board?
In the fictional acquisition, the modelled financial outcomes provide a basis for reviewing integration costs, synergy delivery, customer retention and profitability.
But the board also needs to know who owns the integration, how management capacity will be protected and when corrective action would be taken.
The business case should become part of the management framework for delivering the decision, not disappear into an archive once approval has been granted.
A better test of a business case
For me, the quality of a Case for Change isn't measured by the number of pages, the sophistication of the financial model or how convincingly it argues for the preferred option.
It's measured by whether it helps decision-makers understand what they're committing to.
A strong Case for Change should make seven things clear:
- The decision: What exactly are we being asked to approve?
- The rationale: Why is this the right thing to do, and why now?
- The alternatives: What other credible options exist?
- The economics: What range of financial outcomes is plausible?
- The uncertainty: Which assumptions matter most, and how confident are we?
- The consequences: What risks, resources and competing priorities are involved?
- The accountability: Who will deliver it, how will we monitor progress, and what would make us change course?
For reversible decisions, we can often afford to move quickly and learn.
For decisions that are difficult to reverse, the standard should be higher.
The purpose of a Case for Change isn't to make the recommendation look right. It's to help the organisation make the right decision.
The Risky Insurance Brokers acquisition is entirely fictional and has been developed to illustrate Goose Advisory's approach to strategic decision-making, financial analysis and board governance. The financial outputs are illustrative and should not be interpreted as verified transaction valuations or investment advice.